


At no point since 1945 has the United States accepted a hostile power controlling a strategic sea lane. Andrew Gawthorpe, the Leiden University historian of American foreign policy and author of America Explained, cannot see how it accepts this one.
As he put it to me: this “doesn’t end without the US either using military force to reopen the Strait of Hormuz or definitely calling it a sign of the end of American hegemony — because that would mean accepting something they have never accepted before.”
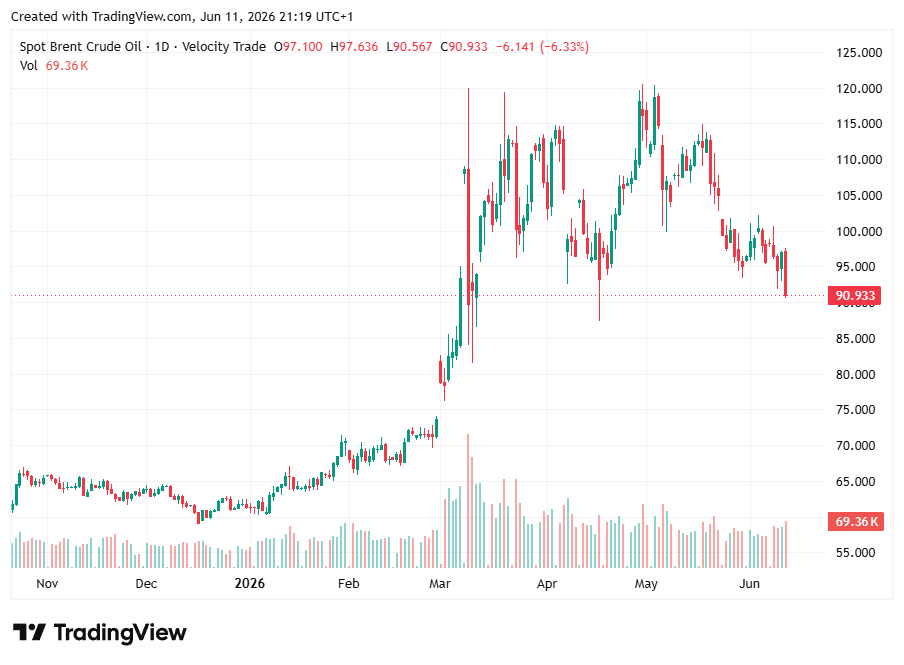
And yet, one hundred and five days into the closure of the Strait of Hormuz, that is exactly what seemed to have happened, and it’s not even clear if that is enough for Iran. All that while the international oil price sits, implausibly, around $90.
Yesterday, Trump’s rhetoric went from “obliterating Iran” to saying “the discussions and final points were approved by all involved.” He was immediately mocked by an Israeli official, who said “We do not recognize reaching an agreement … he has already said 38 times that there is an agreement”
Iranian state media quickly followed in the mocking: “In just three days, he ‘imaginarily’ sent his deputy to Pakistan four times [...] As long as Iran does not itself announce the existence of a possible understanding or agreement, Trump’s reports on the subject should be considered part of his previous line of messages.”
At this point, Trump should be in the Guinness world record book for successive successful ceasefires. While the US is being “humiliated” by Iranian leadership, as per German chancellor Friedrich Merz, markets (or at least, algorithms reading headlines) seem to take Trump seriously.
His comments led to wild gyrations in commodities, with Brent crude dropping more than 5.5 percent within three hours and gold and copper rising about 3.4 and 3.2 percent respectively.
Do you find it difficult to know what to believe? You are not the only one. Due to the nature (and strategic necessity) of wartime propaganda, it is difficult to see for the general public what is actually happening in physical markets and diplomatic negotiations.
Both Iran and the US, and likely various other actors, are working to influence elite and public opinion, with geopolitical and financial interests alike in play. Orchestration or structural financial interests — probably a mix of both. Call it a conspiracy or a media blind-spot; it does not matter. One has only to set media messaging and political strategic communications against what industry insiders are saying to get what’s really going on.
The same goes for the deal itself: whether it signs in Europe next week or joins the other thirty-eight, it does not matter much. A signature supposedly reopens a strait. It does not yet refill a salt cavern. It does not restart lost production. The 1.2 billion barrels are still gone, the rebalancing year still has to be served, and the incredible historical precedent — that Iran closed Hormuz for over a hundred days and paid no price Washington could enforce — is already written into the new order. Because one thing is clear: the people who actually get their hands dirty are panicking, and the data does not lie.
Listen to the men with dirty hands
The warnings from the people who actually move the molecules have been piling up since late May. At the Wall Street Journal CEO Summit, Chevron’s Mike Wirth warned that the market’s shock absorbers were nearly gone, with physical price pressures weeks away. Exxon’s Neil Chapman called inventory levels across crude, gasoline, diesel and jet fuel “unheard-of”, and put Dated Brent at $150–160 once they run dry. Shell’s Wael Sawan put a number on the supply loss: 1.2 billion barrels, a year to rebalance, and named the suppression mechanism: “We are borrowing from the future.”
I hear you thinking: “oil executives would say this, wouldn’t they?” Yes. But not for the reason you think. Oil companies want high prices, but they want them stable. The sweet spot is where you keep buying and they keep selling. A spike to $150-160 wouldn’t be resolved by new investment in production, it would be resolved by demand destruction: consumers and businesses cutting consumption by force of price. That incentivises a permanent shift away from oil. Which is precisely contrary to their interests.
Even Paul Krugman — no oil interests, a renewable-energy advocate — told a crowd at Erasmus University Rotterdam in May that global stocks were draining at six million barrels a day, with minimum operational levels arriving “as early as next month”. I reported on that talk. The fundamentals have not shifted since, as the deal still awaits a signature from both sides and boats need to get moving to remove any mines.
Confused? So am I. Counterintuitively, modern information technology has thickened the fog of war rather than lifted it. As I write, Trump has once again unilaterally announced a deal — his thirty-ninth, by some counts — and yet the strait remains closed:


A paid subscriber and I disagreed on who was in the weaker position. I thought it was the US. He prodded me to investigate, so I followed the market obsessively for weeks, weighing what credible people said against whose interests it served. This week, the data settled it for me. The frenzied deal-making only confirms it: a hegemon does not announce the same victory thirty-nine times unless it badly needs one.
To triangulate, I interviewed three specialists whose analysis runs through this series: Andrew Gawthorpe again; Damon Golriz, an Iran specialist at The Hague University of Applied Sciences and author of Redefined.; and Michel Don Michaloliákos, a geo-economics and Middle-Eastern analyst who co-founded Hague Institute of Geopolitics.
Drawing on those conversations, my conclusion is that things will not return to normal, even after a deal. The stakes run well past commodity markets to US hegemony itself. Any deal may prove temporary, the conflict may reignite — but either way, the security architecture of the Middle East, and the projection of American power, has already shifted tectonically.
This is a historical inflection point. Some analysts reach for the Suez-crisis. I resist the comparison — Suez was above all a financial rout, and the dollar has so far been spared that verdict.1 But the geopolitical substance is the same: a previous hegemon discovering, in public, the limits of its reach. While my interviewees did not want to go this far, I am willing to say that this is the definitive end of US hegemony.2
This first piece shows what’s at stake in the physical energy market. The pieces that follow examine how US decision-making has (mal)functioned under Trump; why the US and Israel so badly misjudged the societal resilience of Iran as a civilisational state; how “Iran can win the war, but must also win the peace”; and how the balance of power in the Middle East is shifting, with global implications.
10 June: the data that sealed it
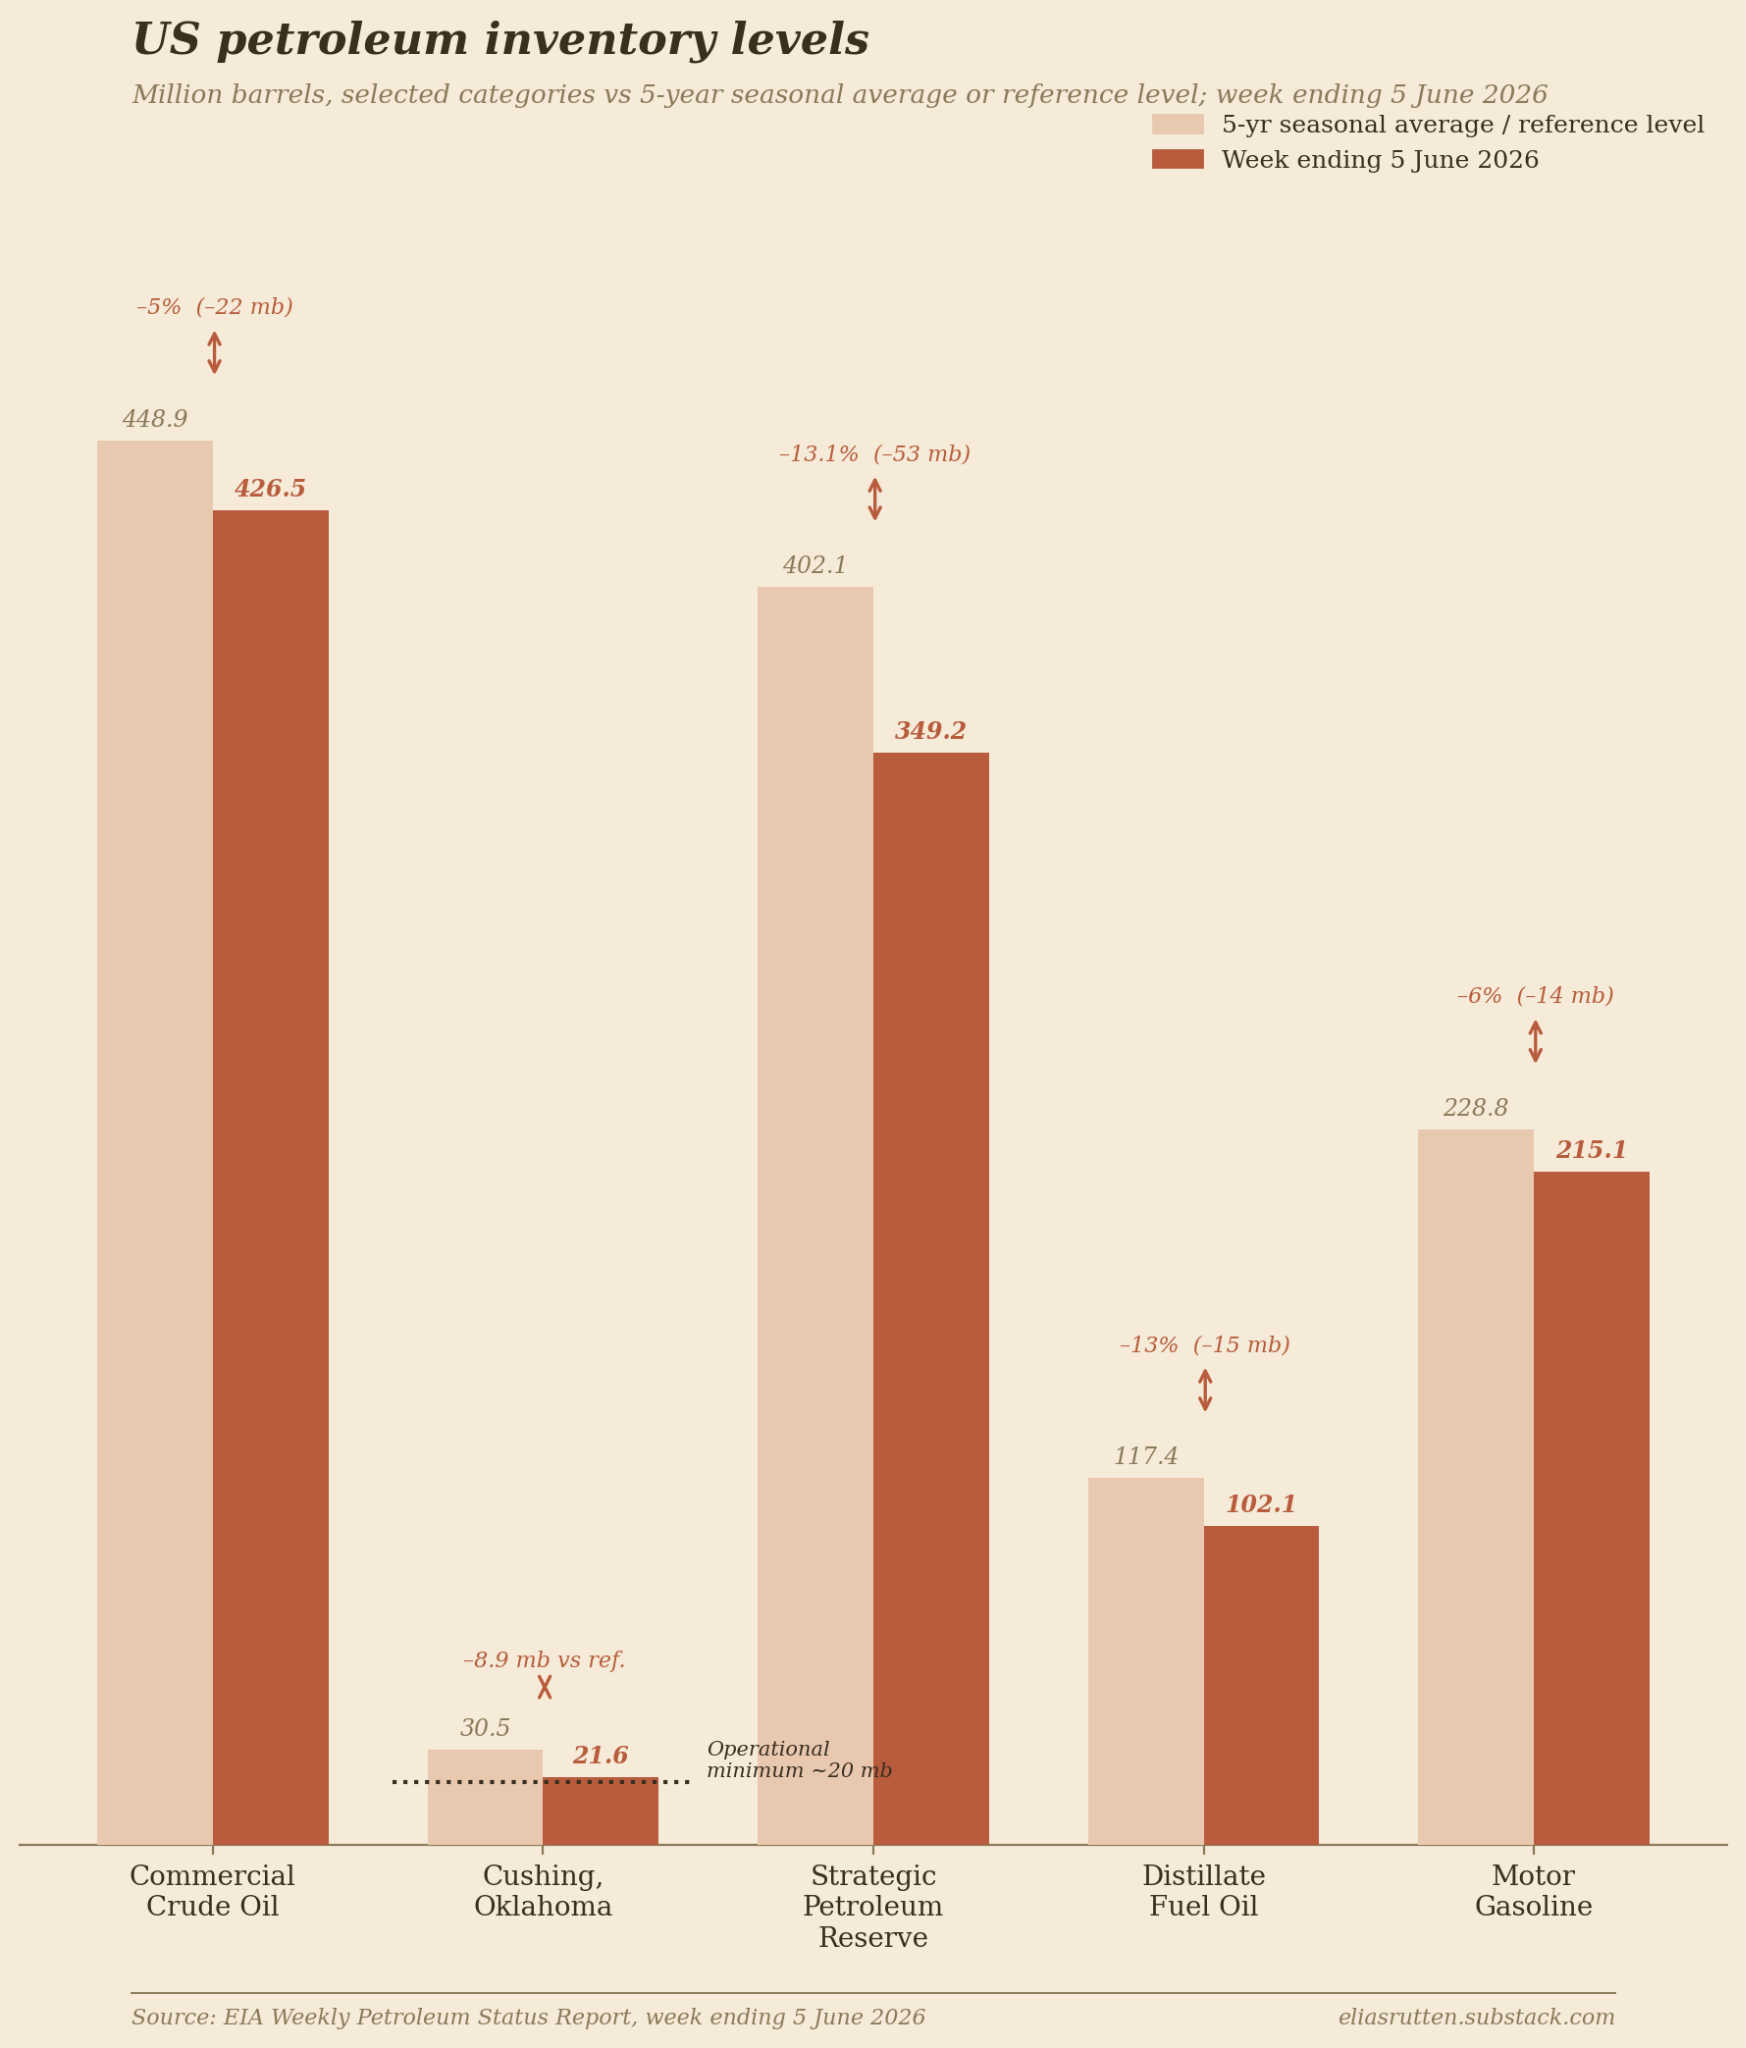
The EIA’s weekly petroleum report, released on 10 June, is not looking good. Distillate fuel oil, diesel, in plain language, is at a 1990 seasonal low, 13 percent below its five-year average. Diesel is the most important fuel in the US economy: trucking, agriculture, construction, rail. All of it uses diesel. Motor gasoline is 6 percent below its five-year average. With refineries almost running at 100 percent capacity, there is almost no spare throughput to rebuild stocks quickly.
I’ve kept all categories on a single scale — which makes Cushing, Oklahoma look like a rounding error next to commercial crude. Don’t be deceived by that, the rate of change is significant. And Cushing is the most important figure in the short-term: it serves as the physical delivery point for West Texas Intermediate (WTI). This benchmark moves the US oil price. The market doesn’t care about relatively immobile commercial crude sitting in Gulf Coast tank farms. It cares about what’s physically deliverable against a futures contract. At a recent draw rate of 0.8 mb per week, Cushing is one week from the level at which pumps can no longer move oil efficiently and the market would tip into backwardation stress. This is why traders watch it obsessively despite it representing a small fraction of total US stocks.
What are futures contracts and backwardation?
A futures contract is a standardised legal agreement to buy or sell an asset at a predetermined price on a specific date in the future. Buyers commit to purchasing, and sellers commit to delivering the asset, regardless of the market price when the contract expires. Backwardation is a market condition in which the current price (spot price) of an underlying asset or commodity is higher than its prices in the futures market. It results in a downward-sloping (inverted) futures curve, signaling that the market is facing immediate supply shortages or unusually high short-term demand.
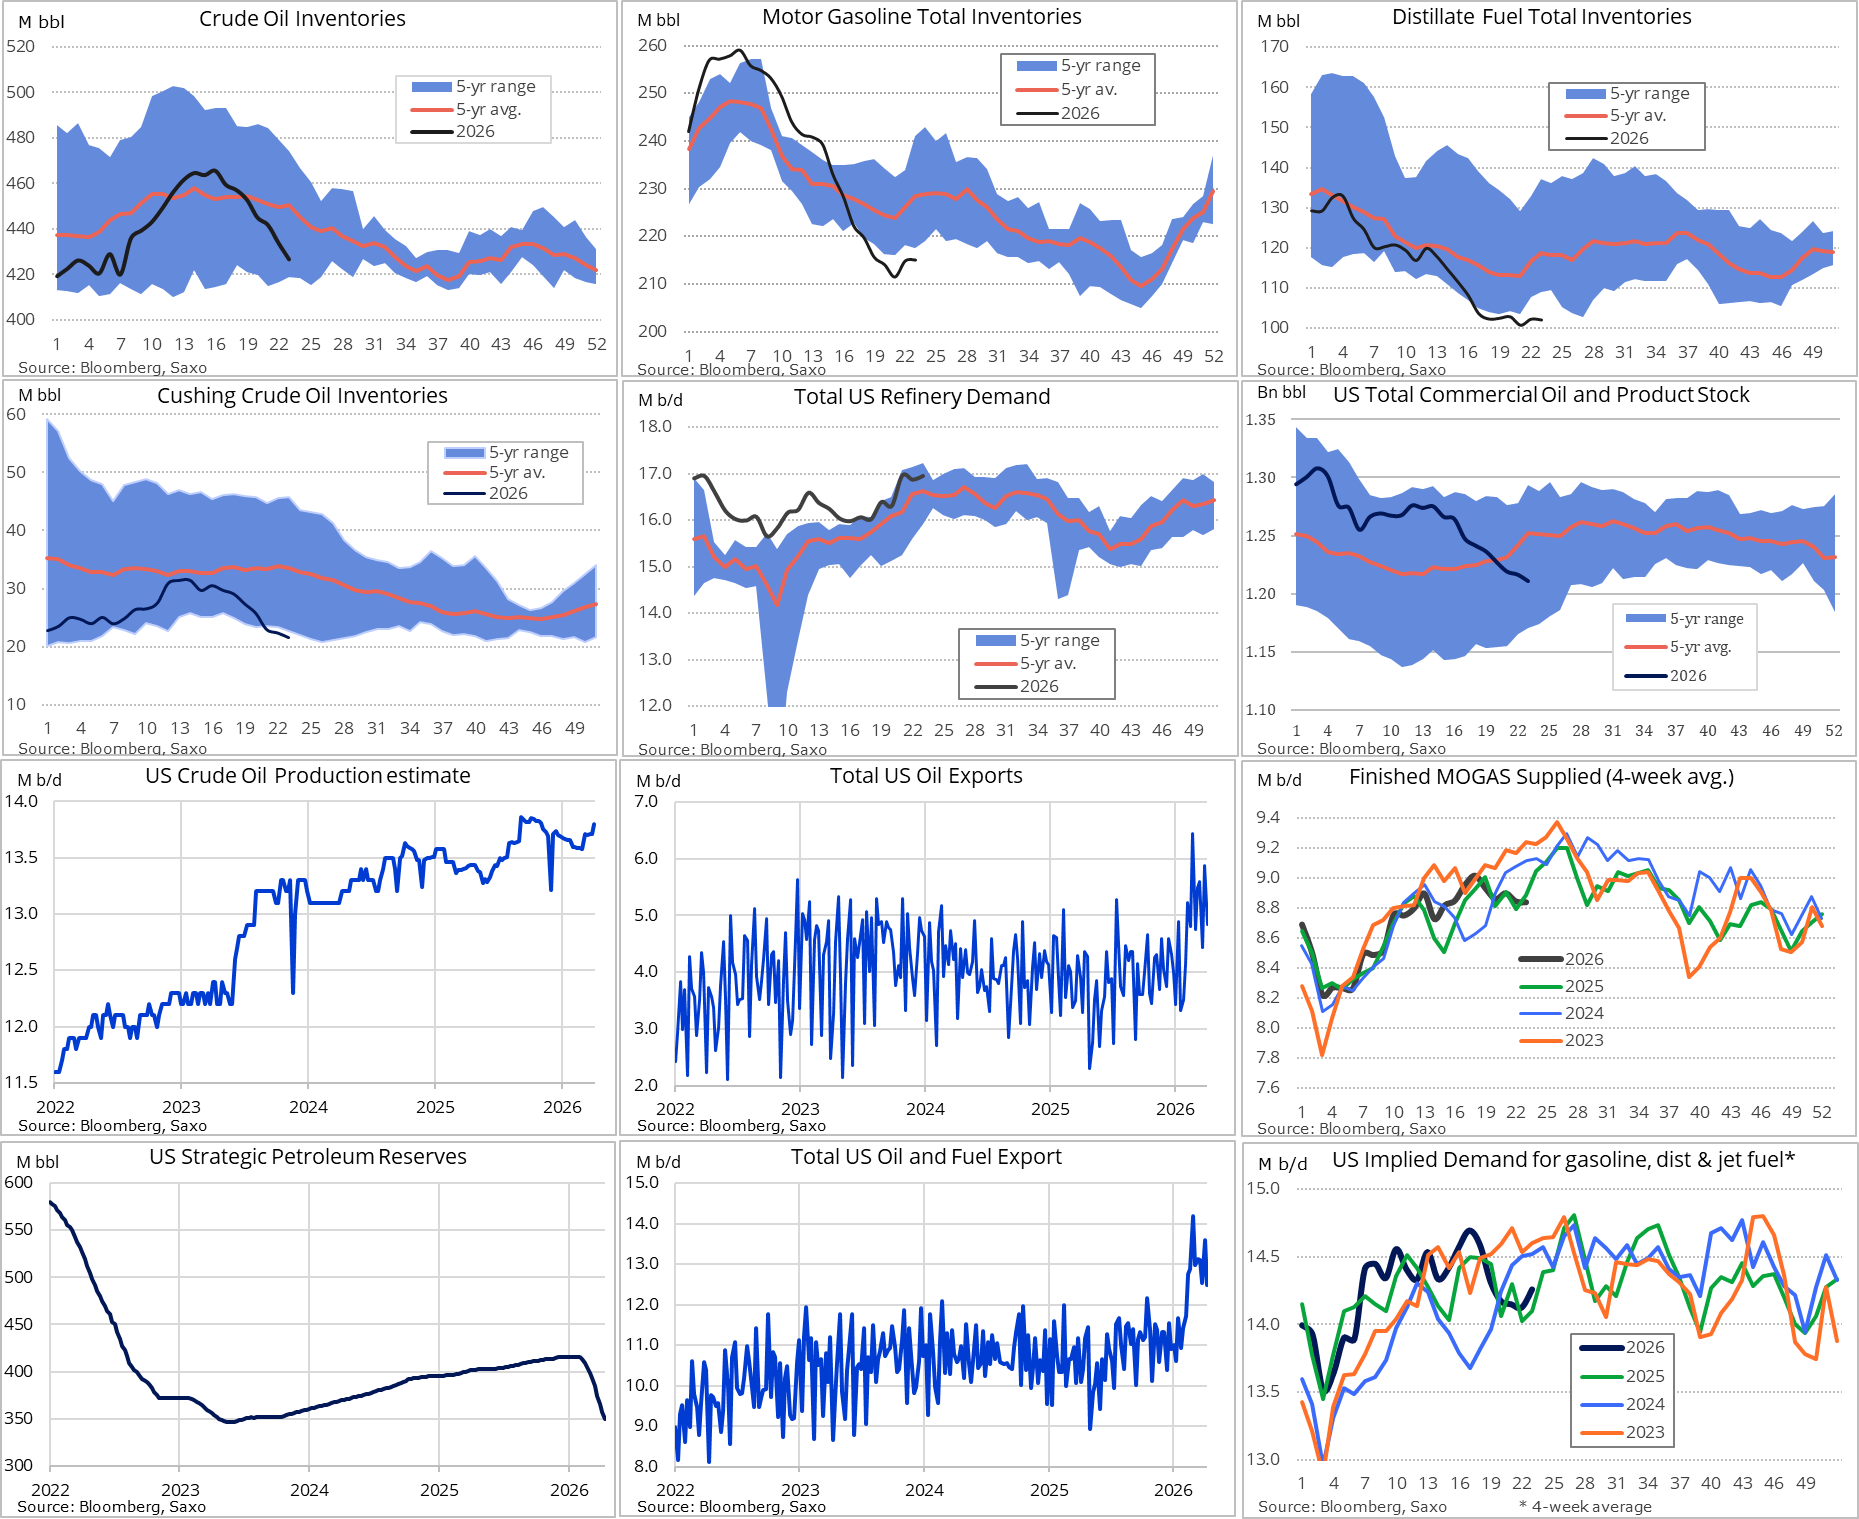
For context, look at where it is sitting at the 5 year average in relative terms on this nerdy chart posted by Ole S. Hansen from Saxo Bank:
One does not simply drain the SPR
Then the SPR drawdown: as we can see on the chart above, the pace of the drawdown is rapid. The SPR lost 7.9 mb in a single week and is down 52.9 mb year-on-year, currently sitting at 349.2 mb. I once again hear you thinking: “349.2 mb sounds like a lot, seems like we’ve got plenty of time”. Based on the execution of this war, Trump might’ve thought that too. But no, one does not simply draw down the SPR below 300 mb.
The SPR is stored in various deep underground salt caverns across four major sites located along the coastlines of the Gulf of Mexico in Texas and Louisiana. Storing the oil in massive, naturally occurring salt domes provides a highly secure and cost-effective method compared to above-ground metal tanks.
But it also comes with a slight logistical problem. The caverns rely on the constant internal hydraulic pressure of the stored crude oil and brine to maintain their shape. If too much oil is drawn out, the massive weight of the surrounding rock can cause the salt walls to warp, shift, or completely collapse inward, permanently destroying the SPR storage. The reserve has a floor, and the floor is made of salt.
The spread says it all
So, this unsustainable drawdown, combined with jawboning (they should make this the word of the year) has come to the benefit of lower oil prices, with WTI (US) and Brent (international) hovering around $87.60 and $90.90 a barrel in spot prices respectively at the time of writing. Lower WTI prices reflect the fact that shipping landlocked US crude to global markets costs money. The spread between the two inverts or narrows when Cushing gets tight.
The spread right now is $3.30, compared to $5.20 on 20 February, a week before the war. That compression reflects exactly what the inventory data shows: Cushing tightness pulling WTI upward toward Brent. A wider spread increase US export incentives, a tighter one decreases it; at $3.30, those incentives remain intact, which means exports continue draining the very hub whose tightness is compressing the spread. But the narrowing spread does reflect empirically the unsustainable nature of this move, and that is shown in the data:
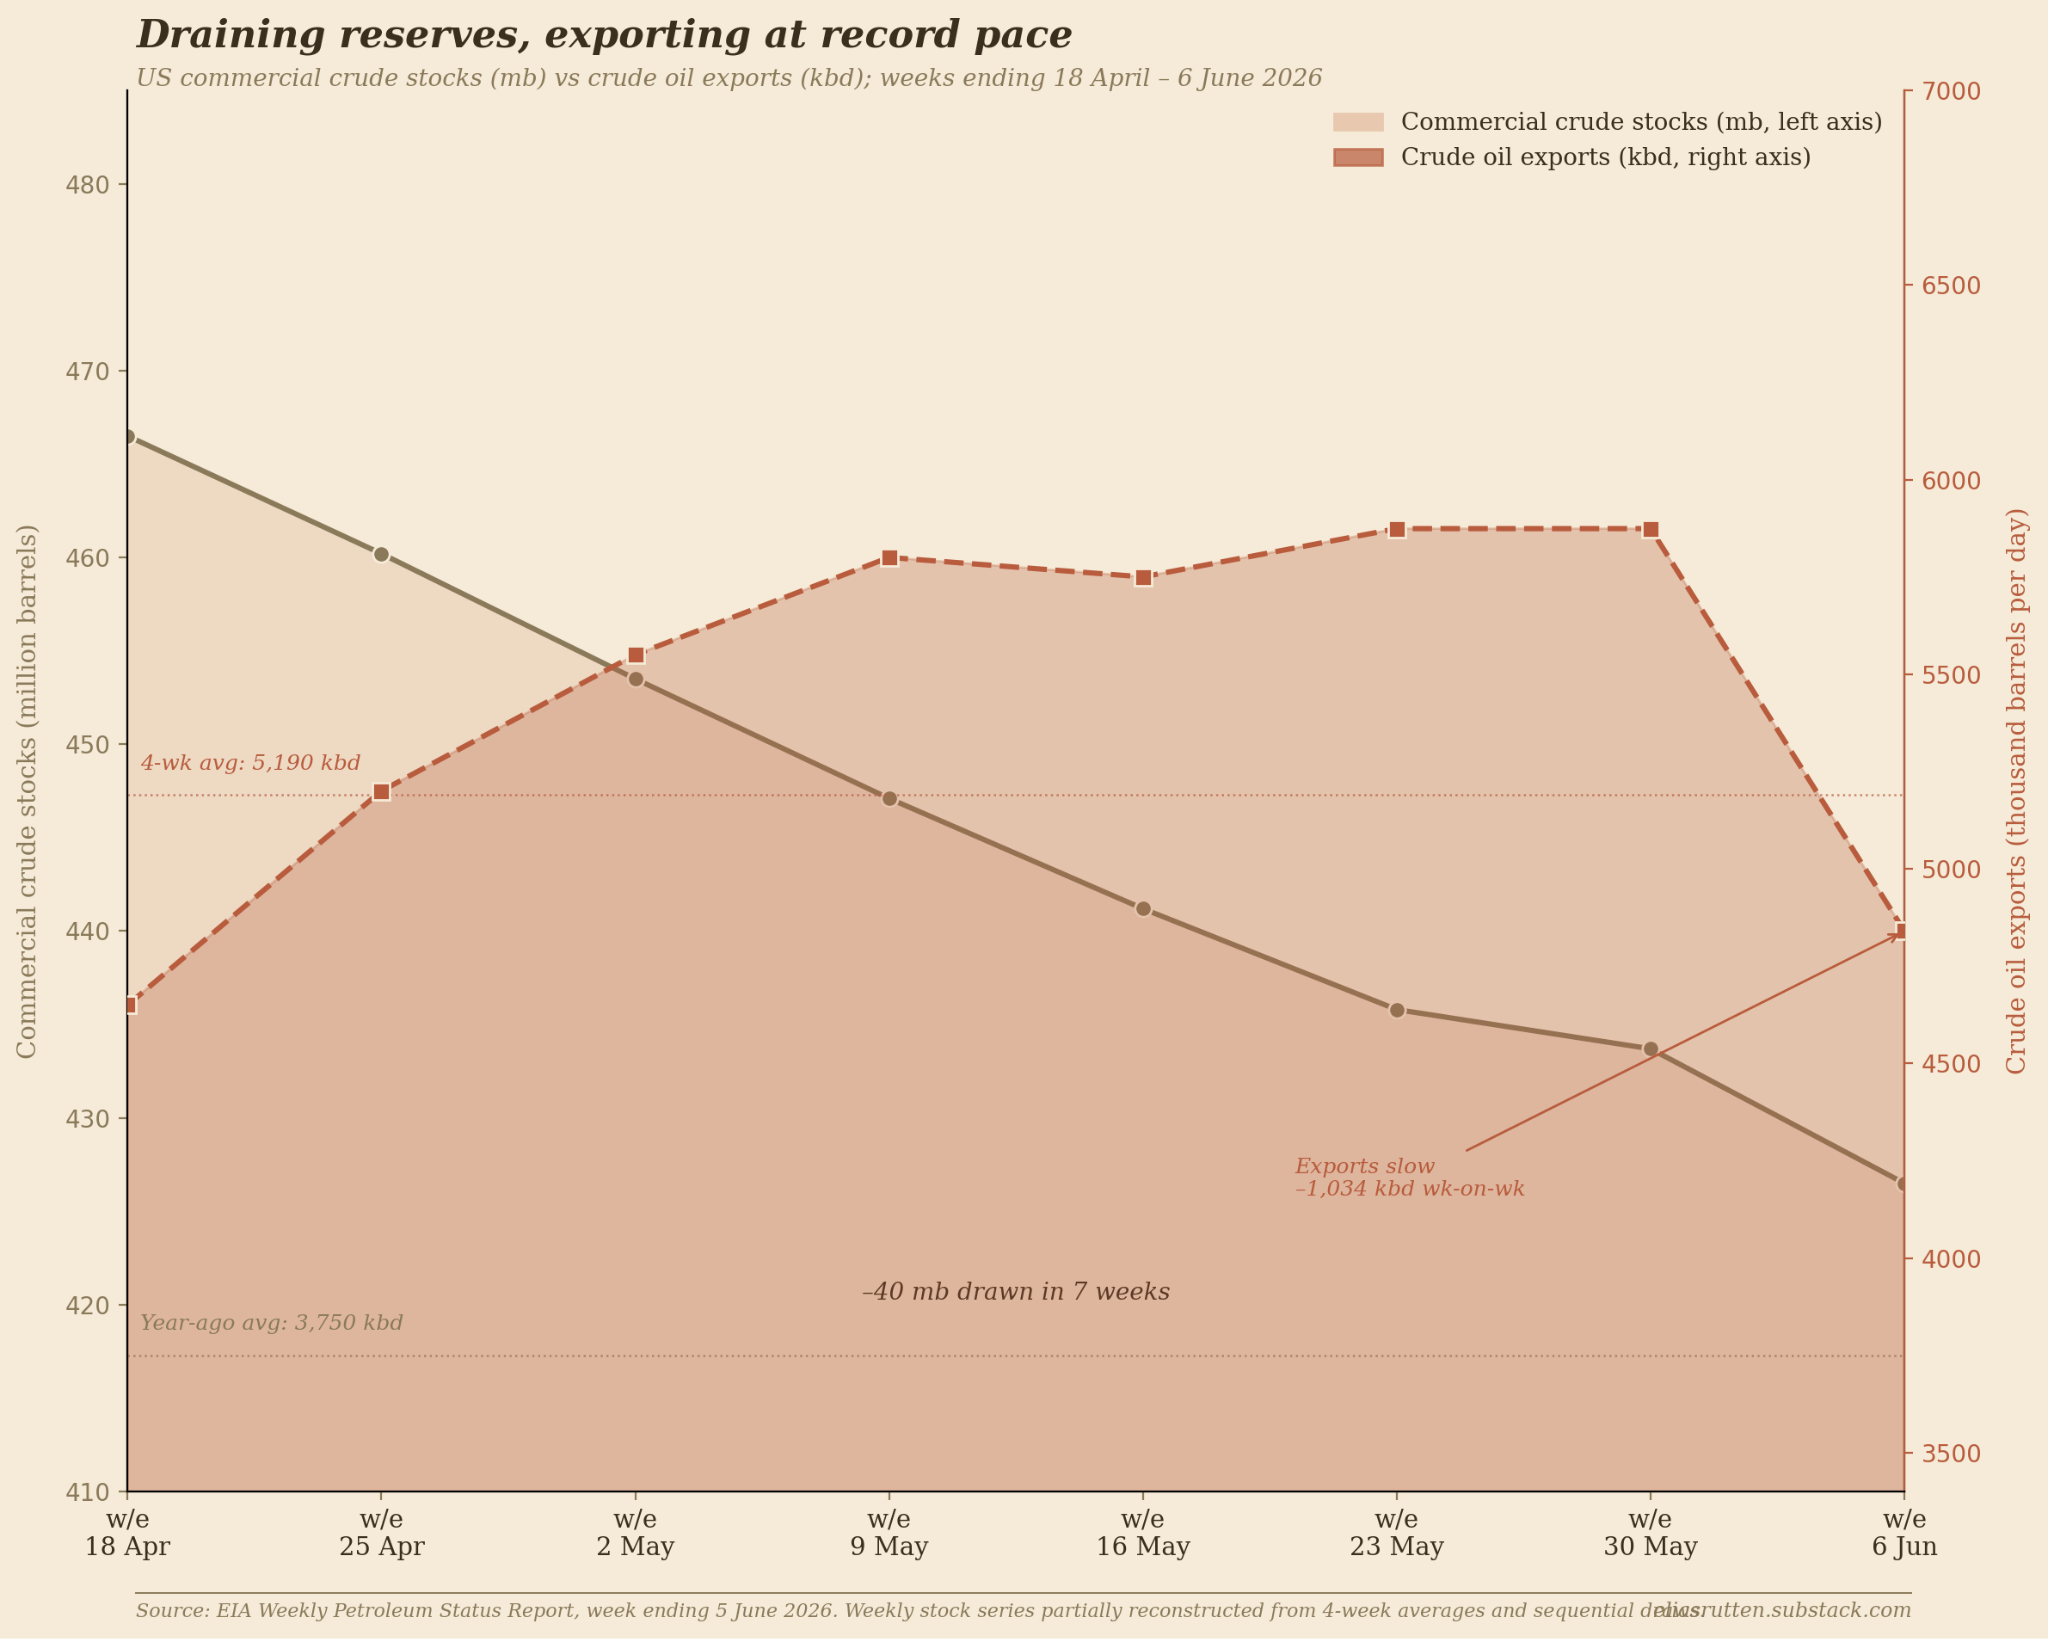
Though US oil exports surged post war, they seem to have slowed down since the 30th of May. If this trend continues, this spells bad news for markets outside of the US. If the spread narrows further, an official export-ban might not even be necessary to cause havoc in global energy markets. And if you’re sitting in the US reading this, feeling relieved: sorry to break it to you, a global recession would hurt America too.
By all appearances, the White House opted for the huge drawdown and export-surge to maintain both domestic support and international tolerance of the US-Israeli war of aggression. With the US functioning as an international stabiliser of the oil market, while drawing down on reserves aggressively to maintain low gasoline prices at home. Yet, European governments, meanwhile, are juicing demand beyond what market prices justify, shielding households through energy subsidies. The arithmetic shows in the reserves drawdown. No matter what the narrative is, this number is what everyone should be watching. This course of action indicates that the White House had expected this war to last far shorter than it has — a Putinesque gambit. The two men have similarities, but Trump lacks the evil genius of Putin — though they have both miscalculated and underestimated an apparently weaker enemy.
Trump’s impossible choice
As long as the crisis remains unresolved, Trump is stuck. He either lets Americans pay for the war at the pump, or he imposes export restrictions and torches what remains of Washington’s standing as guarantor of open energy markets. One might think that an easy choice. It is anything but. An export ban would do what no Iranian missile could: convert a US supply problem into a global financial event.
Japan’s financial system is already holding on to dear life, partially as a result of the commodity shock, as I’ve described in a previous post, and Europe’s energy-subsidising governments are borrowing into the same storm. A shock of that size loops back into US financial markets through the Treasury market, through the dollar funding system, through everything. There is no firewall. Eventually, the real economy and financial economy run on the same pipe: you can’t print more molecules.
How did the White House manoeuvre itself into this corner? Part of the answer is a structural dismantlement of internal checks and balances, and I’ll get to it in the next piece with Gawthorpe. Part of it is the man himself.
Most of the establishment — the Pentagon included — understands this has been a disaster, says Gawthorpe. Trump does not, because he has built a bubble in which objective voices simply don’t reach him. The family and loyalists who do are telling him Iran’s new leadership is isolated and ineffective, the damage enormous. “He just won’t admit it was a disaster. I think you’ll never see him willing to put out a statement that truly reflects where things stand, because that would be to admit defeat.”
The conclusion Gawthorpe draws is blunt: “Trump has effectively ceded the Strait of Hormuz. And in doing so, he has demonstrated a real weakening of American power in this era.”
What this war reveals, in his reading, is that global competition is no longer about territory and population. It is about chokepoints, supply chains, and geoeconomic nodes. “Trump going to war in service of this twenty-year-old agenda about Iran having a nuclear weapon, and ending up in a war that is really about a key choke point in the global economy — that’s an old way of thinking colliding with new realities.”
As the Iran expert Damon Golriz said aptly: “America’s got the clock, Iran’s got the time.”
In 1988, it was Iran’s supreme leader Ruhollah Khomeini, who ended a war by drinking what he called a poisoned chalice. Golriz’s prediction, which I’ll unpack later in this series: this time, the chalice is being prepared for Trump.
Pieces like this one take weeks of passive research, days of primary interviews, and more reviewing of data than I care to admit. After all, I want to give you correct and qualified infomation After this series, prices rise to €8/month and €80/year, with more in-depth work moving behind the paywall. If you’ve read this far, you know what you’d be paying for. Now is the time.
Thank you for reading. I write this between deadlines, on my own time. If it was worth yours, buying me a coffee would mean a lot.
Though the analogy is fitting because of the chokepoint control, it is a fundamentally different dynamic with a former hegemon being checked by a new hegemon. Suez is often invoked to signal the final nail in the coffin of Sterling dominance. The UK and Sterling were in a much tougher position at the time than the dollar is now. Firstly, WW2 devastated the British economy, Bretton Woods formally shifted hegemony to the dollar, and the 1945 Anglo-American loan confirmed dependency. In the modern day, US dollar hegemony is doing well, I’d say. There is no national threat to the dollar, the only observable shift is away from dollar reserves towards gold — yet international settlement still occurs in dollars and dollarization is in fact accelerating through stablecoins, and there are many new avenues for monetary attack. This will be discussed in one of my future pieces.
Hegemony is a contested concept in International Relations. I use it in the Gramscian sense: leadership exercised through consent rather than coercion, in which the hegemon’s rules, institutions, and norms are accepted as legitimate by subordinate states, not merely obeyed under duress. Coercion, on this reading, is by definition a symptom of eroding power: the moment a hegemon must make its dominance visible to be recognised, it has already begun to lose it.
This distinguishes the concept from its realist usage, in which hegemony simply denotes preponderant material capability such as military reach, economic weight, and control of key institutions. Susan Strange’s structural power framework sits somewhere between the two: the hegemon is whoever controls the structures within which others must operate, above all the security structure, the production structure, the finance structure, and the knowledge structure.
Cox’s formulation is perhaps the most precise for present purposes: hegemony is a world order in which the dominant power’s interests are generalised as universal interests. The moment that universality is visibly contested the order itself is in question, not merely the hegemon’s reputation. The reason analysts are hesitant to go on a limb and say that hegemony is over, is because when they eventually book a success, they get clowned on. Granted, US hegemony in the financial structure is still very much in-tact and may be strengthening as highlighted in the footnote above — which is something I will explore in a future piece. The point is that these spheres all interact to provide a singular historical structure, that is a form of world order.
Granted, US hegemony in the financial structure is still very much intact and may be strengthening as highlighted in the footnote above — which is something I will explore in a future piece. The point is that these spheres all interact to provide a singular historical structure, that is a form of world order.
Trump MAGA Republican 2024 campaign rhetoric “Regime change is a proven, absolute failure.” Yep! Absolute failure costing billions and American lives as loss of life in the region. Defeat or stalemate of conflict in the region in the confrontation with Iran will have lasting severe international disruptions. Agree, this is likely the end of the American hegemony in world affairs, perhaps starting in 2003 with Bush Iraq war. As Australia’s former Prime Minister Malcolm Turnbull commented “Trump has already demonstrated that the U.S. cannot be trusted!”
I’ve been beating this same drum since the end of April, when the longer term economic impact really hit home
This war was a fundamental mistake
Staying in it and not just walking away in April or early May with some face-saving declaration of victory is even more so
Any military analyst worth the name could have told the administration the first
Any economist with an eye on global supply chains could have told them the second
The next year or three is not going to be fun, anywhere in the planet